Self-Employed in Winnipeg? How to Navigate the Mortgage Process
Understanding Lender Requirements for Self-Employed Borrowers
Securing a mortgage can feel like a complex journey. For Winnipeg’s vibrant community of entrepreneurs, freelancers, and small business owners, it often presents a unique set of challenges. Unlike those with traditional salaries, self-employed individuals navigate different income structures. This can impact how lenders assess their eligibility. The good news is that homeownership is absolutely achievable with the right strategy and expert guidance.
Understanding self-employed mortgage requirements Canada Winnipeg is the first step. Lenders often perceive self-employed individuals as higher risk due to potentially fluctuating income and the absence of traditional employer verification. Therefore, they look for stability, consistency, and a reliable financial track record. Most lenders typically require a minimum of two to three years of self-employment history to assess income stability. By exploring various mortgage options for self-employed Canada, you can find a solution tailored to your business structure.
Essential Documents for Income Verificatio
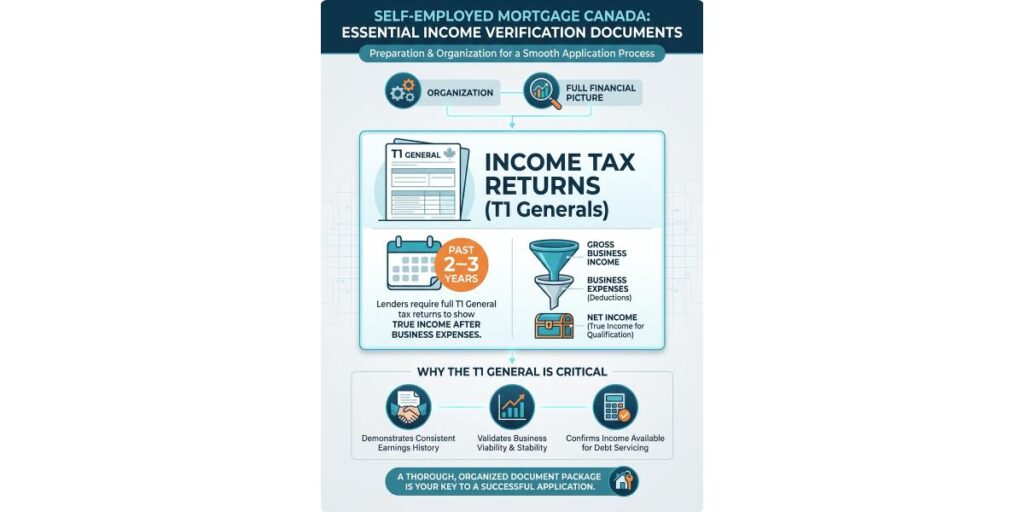
Preparing thorough documentation is crucial for a smooth application process. When it comes to income verification for self-employed mortgage Canada, organization is your best friend. Lenders want to see the full picture of your financial health.
Here are the essential documents needed for self-employed mortgage Canada applications:
- Income Tax Returns (T1 Generals): Lenders require your full T1 General tax returns for the past two to three years to show your true income after business expenses.
- Notices of Assessment (NOAs): You will need your NOAs from the Canada Revenue Agency to verify your reported income and confirm no outstanding tax balances.
- Financial Statements: If your business is incorporated, accountant prepared financial statements for the past two years are typically required.
- Bank Statements: Providing three to twelve months of personal and business bank statements demonstrates consistent cash flow.
If you have significant business write-offs that reduce your taxable income, you might be a candidate for the Stated Income Program Canada mortgage self-employed. This option allows you to declare your income without providing extensive tax documentation, provided you have a strong credit score and a larger down payment.
