How to Boost Your Credit Score Before a Mortgage Application
Why Your Credit Score Matters for Mortgage Approval
When you are preparing to buy a home in Winnipeg, your credit score is one of the most critical factors lenders evaluate. A strong credit rating not only increases your chances of approval but also unlocks the best interest rates available. As an experienced mortgage broker in Winnipeg, Manitoba, Laurie Boudreau has spent over 20 years helping thousands of clients navigate the complexities of home financing. Whether you are a first-time buyer or looking for mortgage refinancing, understanding how your credit impacts your borrowing power is the first step toward homeownership.
Lenders use your credit score to gauge financial responsibility and assess the risk of lending you money. If your score is on the lower end, do not panic. Laurie specializes in finding mortgage solutions for everyone, including those with credit challenges, minimal income, or little savings. However, taking proactive steps to boost your credit score before submitting a mortgage application can save you thousands of dollars over the life of your loan.
Actionable Steps to Improve Your Credit Rating
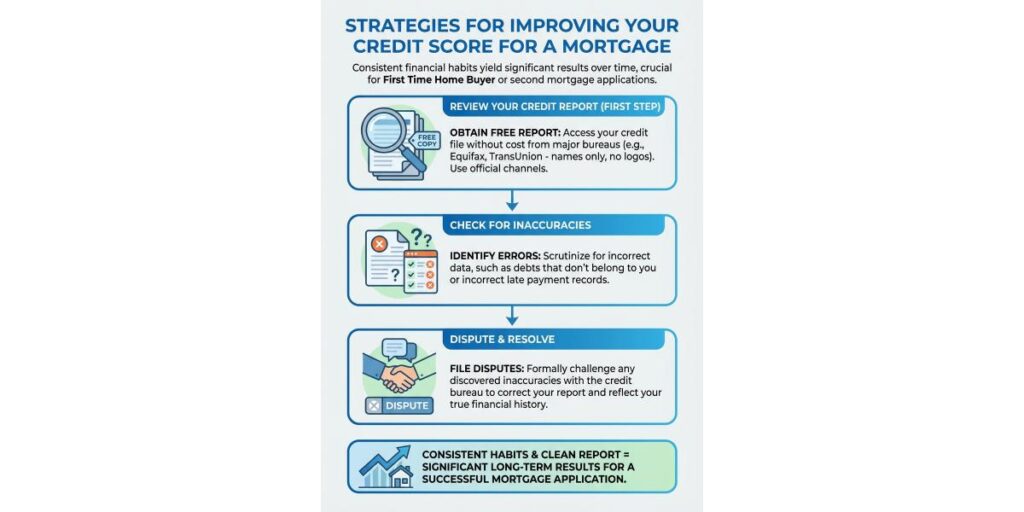
Improving your credit score does not happen overnight, but consistent financial habits will yield significant results. If you are planning to apply for a First Time Home Buyer Mortgage or even a second mortgage, consider implementing these proven strategies:
- Review Your Credit Report: Obtain a free copy of your credit report from major Canadian credit bureaus like Equifax or TransUnion. Check for any inaccuracies, such as debts that do not belong to you or incorrect late payments, and dispute them immediately.
- Pay Your Bills on Time: Your payment history is the largest component of your credit score. Set up automatic payments or calendar reminders to ensure you never miss a due date.
- Reduce Your Credit Utilization: Aim to keep your credit card balances below 30 percent of your total available limit. Paying down revolving debt shows lenders that you are not over-reliant on borrowed money.
- Avoid Opening New Credit Accounts: Each time you apply for new credit, a hard inquiry is placed on your report, which can temporarily lower your score. Hold off on financing a new car or opening store credit cards until after your mortgage closes.
- Keep Old Accounts Open: The length of your credit history matters. Even if you no longer use an older credit card, keeping it open with a zero balance can positively impact your credit age.
By following these steps, you will be in a much stronger position when it is time to sit down with a Winnipeg mortgage specialist.
